Arson Fire at Ontario Warehouse: What Every Building Owner Must Review in Their Insurance


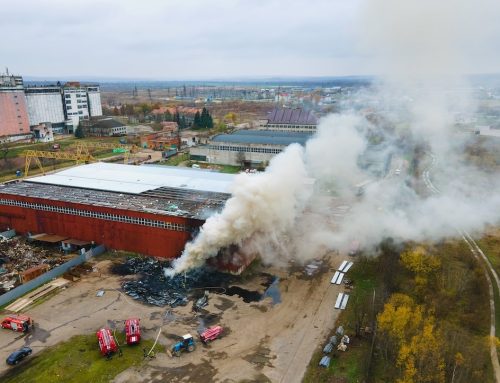
This week, a massive warehouse fire in Ontario—suspected to be caused by employee arson—resulted in the total destruction of a 1.2 million sq. ft. facility. The fire spread rapidly, leading to a complete structural collapse and significant financial loss.
For commercial property owners, this incident highlights a critical question:
👉 If this happened to your building, would your insurance fully protect you?
What Insurance Coverage Applies for Building Owners?
1. Commercial Property Insurance (Core Protection)
This is your primary line of defense.
Covers:
- Building structure
- Roof, walls, foundation
- Permanent fixtures (electrical, plumbing, HVAC)
In this case:
- The entire warehouse structure would be a covered loss due to fire
⚠️ Important:
Even though the fire was intentionally set, coverage applies as long as the owner is not involved.
2. Loss of Rental Income (Rental Value Coverage)
One of the most overlooked but critical coverages.
Covers:
- Lost rental income during repairs/rebuild
- Ongoing expenses (mortgage, taxes, insurance)
For a large warehouse:
- Rebuild could take 12–24 months
- Loss of income can exceed the property damage itself
3. Ordinance or Law Coverage
After a total loss, rebuilding isn’t simple.
Covers:
- Demolition of damaged structure
- Increased cost to rebuild to current building codes
👉 Older buildings are especially exposed here.
4. Liability Exposure (CGL Policy)
If the fire spreads beyond your property:
Covers:
- Damage to neighboring buildings
- Bodily injury to third parties
Even if you didn’t cause the fire, you could still be pulled into lawsuits.
5. Tenant Risk & Lease Transfer
In many warehouse leases:
- Tenants are responsible for certain risks
However:
- If insurance requirements are not properly structured, the landlord may still absorb the loss
Key Coverage Gaps Building Owners Often Miss
1. Incorrect Building Valuation
- Construction costs have increased significantly
- Many buildings are underinsured
2. Lack of Ordinance or Law Coverage
- Rebuilding to code can increase costs by 20–40%+
3. No Rental Income Coverage
- Owners focus on physical damage but ignore cash flow risk
4. Weak Lease Insurance Requirements
- Tenants may carry:
- Low liability limits
- No proper additional insured endorsements
Insights from the Ontario Warehouse Fire
1. You Can’t Control Tenant Behavior
Even a single employee can cause catastrophic damage.
2. Total Loss Is a Real Scenario
This was not partial damage—the building was completely destroyed.
3. Recovery Takes Time
- Permits
- Debris removal
- Reconstruction
👉 All delay your income stream.
Final Thoughts for Building Owners
Owning commercial property is not just about collecting rent—it’s about protecting a long-term asset.
This incident is a reminder that:
- Fire risk still exists—even with modern systems
- Internal threats (like employee arson) are unpredictable
- Insurance must be structured for worst-case scenarios
📞 Call to Action: Protect Your Investment
Don’t wait until a loss happens to find out where the gaps are.
Contact us today to review your existing policies, including:
- Building replacement cost
- Rental income protection
- Ordinance or law coverage
- Tenant insurance requirements
Our team will help ensure your property is fully protected and properly structured—so you can recover with confidence, even after a catastrophic loss.
Contact your local TransGlobal today or call 888-831-8868.
>>Fill Out the Inquiry Form Now<<
A personalized plan will be created for you!