
Mortgage Market Update

mortgage
Changes are coming to some mortgage fees
Fees on mortgages backed by Freddie Mac and Fannie Mae are set to change next month, in a plan designed to make homeownership more affordable for more people. Broadly, the fees will go down for many with lower credit scores and will increase for many with higher credit scores.
But that doesn’t mean people with lower credit scores will pay less than those with higher credit scores. The changes mean that people with higher credit scores will still pay less based on lower risk to the lenders, but having a lower credit score will now come with less of a penalty.
There are many variables that go into the cost of a home loan, including what kind of property you are buying, how much money you’re putting down and how high or low your credit score is.
These variables help lenders — and government-backed Freddie and Fannie, which buy the vast majority of loans from lenders — price loans for risk. After starting with the basic, or par, rate, additional price adjustments are added in order to account for how risky the loan is for lenders to make.
Pricing hits like this are called a loan level price adjustment, or LLPA, and have been around for a while and are occasionally updated. The price adjustments allow Freddie and Fannie to keep from being undercapitalized and over-exposed to risk. Fannie and Freddie, which guarantee roughly half of the country’s mortgages, do not directly issue mortgages to borrowers, but instead buy mortgages from lenders and repackage them for investors.
Changes to existing fee structure
Last year the Federal Housing Finance Agency, which oversees Freddie and Fannie, increased the fees on loans for which there is less reason for government support, including some high balance loans, vacation homes and investment properties.
In October, the FHFA announced it would eliminate upfront fees for certain borrowers and affordable mortgage products, who tend to be borrowers with limited wealth or income, while putting in place increases to other fees, specifically for most cash-out refinance loans.
Then, in January, the FHFA announced additional updates to the fee structure for single-family homes that made permanent the eliminated fees and spelled out how other fees would be increased.
“These changes to upfront fees will strengthen the safety and soundness of the enterprises by enhancing their ability to improve their capital position over time,” Sandra L. Thompson, director of FHFA said at the time. “By locking in the upfront fee eliminations announced last October, FHFA is taking another step to ensure that the enterprises advance their mission of facilitating equitable and sustainable access to homeownership.”
How the fee change works
For those with lower credit scores, the fee changes will reduce the penalty for having a low score. For those with higher credit scores, more price tiers have been put in place, which in some cases may increases fees.
For example, a buyer who made a 20% down payment with a credit score of 640 would see their fee drop 0.75% from 3% to 2.25% with the updates. Another buyer, also making a 20% down payment, who has a credit score of 740, would see their fee climb by 0.375%, from 0.5% to 0.875%.
The fee will still cost the home buyer with the lower credit score more.
A buyer with a 640 credit score and an 80% loan-to-value ratio will have a fee of 2.25%, while a buyer with a 740 score will have a fee of 0.875%. The difference in assessed fees is about $4,000 more for a buyer with a 640 credit score than for a buyer with a 740 credit score, based on a $300,000 mortgage.
The table outlining the fees based on loan to value ratio and credit score have been posted by Freddie Mac and Fannie Mae.
TransGlobal, professional and complete All-In-One service for the clients to enjoy. Services from life insurance, annuity, and financial management, to now encompassing mortgage financing, real estate, asset management, health insurance, property & casualty insurance, tax services, and family office & wealth management.
Please contact the local agent of TransGlobal today or call 888-831-8868.
>>Contact Us<<
Your plan will be customized by a professional!
Today’s Rate
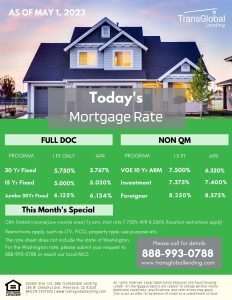
Daily rate based on: SFR/Primary/LTV60/FICO 780/Purchase
IMPORTANT: Advertised rates were valid and effective as of the date reflected above, are for informational purposes only, and are subject to change without notice.
Loans are subject to credit and collateral approval. Advertised rates are based on a set of loan assumptions including a borrower with excellent credit history and optimal loan characteristics. Your final interest rate and annual percentage rate (APR) may differ depending on your individual transaction’s specific characteristics, and certain products may not be available for your situation. Several determining factors include, but are not limited to, the state of the property location, loan amount, documentation type, loan type, occupancy type, property type, loan to value, and credit score.
APR reflects the cost of credit over the term of the loan expressed as an annual rate. For mortgage loans, APR may include the interest rate, discount points (also referred to as “points”), and other charges or fees (such as mortgage insurance and origination fees), but does not necessarily take into account other loan-specific finance charges you may be required to pay.
Golden Star, Inc. dba Transglobal Lending, 185 W. Chestnut Ave., Monrovia, CA 91016, NMLS # 1437002 (www.transgloballending.com). All rights reserved. Equal Opportunity Employer and Equal Housing Lender. All mortgage products are subject to credit property approval. Rates, Program terms and conditions are subject to change without notice. Additional conditions, qualifications, and restrictions may apply. This is not an offer for extension of credit or a commitment to lend.


